The LQG 2024 Autumn Seminar – Hybrid
LQG 2024/09/04 to 2024/09/07 In-Person and On-Line
at
Robinson College, Grange Road, Cambridge CB3 9AN
The Outline Agenda
Scroll down for speakers and topics.
Download the Summary Agenda / Download the Detailed Agenda
Arrive on the afternoon / evening of Wednesday the 4th September 2024 (2024/09/04) to enjoy a welcome buffet.
Starting on Thursday the seminar will be held in Robinson College’s “CWB” the Crausaz Wordsworth Building, an amazing space in which we will enjoy the research and insights of eleven speakers of international renown. The all important speaker rankings – assessed by in-person attendees – will be announced at the final dinner in Robinson College on Friday night.
On Saturday you can take advantage of the opportunity to enjoy a stroll around Cambridge and possibly some punting along “The Backs” on the river Cam.
Experienced LQGers please note that the 2024 seminar format does not allow for the punting challenge to be an integral part of the seminar as it has been in previous years.
Robinson College has delightful grounds and facilities close to the centre of Cambridge. The seminar room is marvellous: The college bedrooms rooms can be seen here :
One ticket – for the seminar, meals and accommodation
All room bookings are for 3 nights including the Friday night.
Guests: Should you wish to bring a guest, please buy an additional guest ticket to cover the social events and meals only. No seminar attendance is included with the guest ticket.
There is car parking available. If you need parking it is important that you buy an additional parking only ticket.
There are some twin rooms available. Please only book a twin if you really need one.
Technology allowing all seminar sessions will be made available to the on-line audience.
The LQG looks forward to you joining the seminar.
To book your place use the red Access Code in the invitation sent by e-mail to those on the LQG mailing list which you can join by using the Sign Up menu option above.
Register for the In-Person seminar here. The all-inclusive in-person seminar fee includes the seminar, accommodation in a single room with en-suite facilities and all meals. A few twin rooms are also available at modest incremental cost. Guest tickets are available to join the social activities only.
Register for the On-Line seminars here. The support of the LQG’s sponsors, BlackRock, Snowflake, Bloomberg and especially the vision of LQG chairman Ed Fishwick means that the entire LQG autumn seminar will be available to on-line LQGers for free.
Voluntary donations to support the LQG are happily accepted when you register.
The London Quant Group (LQG) is a seminar organiser which contracts with Cambridge Colleges for the use of facilities; this event otherwise has no connection or association with the University of Cambridge or its Colleges.


Speakers, talk titles, abstracts and speaker biographies.
Click on the title or speaker name to reveal the abstract / summary.
Venue: Robinson College, Grange Road, Cambridge CB3 9AN
Seminars will be delivered in the Crausaz Wordsworth Building – “The CWB” on the Robinson College site map.
Click here to download the Summary Agenda / Click here to download the Detailed Agenda
Leverage Dynamics and Learning about Economic Crises
Models of learning about economic crises generate risk premia that rise at the onset of a crisis, but then fall as belief uncertainty fades. In contrast, empirical risk premia remain elevated during crises. We resolve this tension via leverage dynamics generated by the impact of learning on optimal default and capital structure decisions within a representative agent consumption-based model. Endogenously time-varying leverage creates a feedback loop: the learning-induced slow recovery in equity prices raises leverage, thereby further depressing equity values and keeping the equity premium and credit spreads persistently high as the crisis unfolds. We structurally estimate the model and show it closely matches the joint dynamics of consumption, equity risk premia, credit risk, and leverage, especially during crises, together with the term structure of credit risk and default probabilities.
Harjoat Bhamra Associate Professor of Finance Imperial College Business School
 Professor of Finance
Imperial College Business School
Harjoat Bhamra is a Professor in Finance at Imperial College Business School. He holds an MA and MMath in Mathematics from St John’s College, Cambridge University and a PhD from London Business School. Prior to joining Imperial, he was an Associate Professor at the Sauder School of Business at the University of British Columbia. His research focuses on financial markets, especially the importance of household heterogeneity for asset returns and the interconnections between asset prices, corporate financial decisions, and monetary policy. He has held visiting positions at École polytechnique fédérale de Lausanne and Goethe University, Frankfurt. He is a Research Fellow at CEPR, an Associate at the Centre for Macroeconomics at the London School of Economics and Political Science, and an Associate Editor at Management Science.
Will AI take all the work (and fun) out of investment?
Observations from a few decades investing a lot of other people’s money with care, creativity, and computation.
Quants are the current forerunners of using mathematical models in investment. How far can and should we go in delegating understanding, creativity and responsibility?
Is AI the democratisation of modelling?
Antonia Lim - Cross-asset investment leader

Antonia Lim
Cross-asset investment leader
Antonia Lim, CFA is a global cross-asset investment leader with over 20 years of experience, innovating investments and transforming businesses with quant and tech.
At Schroders, Antonia was Head of Quantamental Investments and created the equity solutions business to efficiently customise institutional fundamental and thematic segregated mandates. She spearheaded a 100-person program to enhance sustainability measurement and SFDR ESG integration.
Previously, as Global Head of Quantitative Research at Barclays, Antonia oversaw the strategic end-to-end investment process for $180bn, including proposition design, multidisciplinary research, asset allocation, implementation, risk management, governance, and communication.
Antonia’s multidisciplinary team earned Wealth Briefing’s “Outstanding Contribution to Wealth Management Thought Leadership” award. Her pioneering approaches led to her receiving recognition as one of Business Insider’s “Top 100 People Transforming Business”.
Antonia holds a Masters in Physics from the University of Oxford, is a member of the CFA Institute’s Research & Policy Technical Committee, frequently speaks at international conferences and contributes to leading publications on purposeful, quantitative and multidisciplinary investment.
Markowitz Portfolio Construction at 70
More than seventy years ago Harry Markowitz formulated portfolio construction as an optimization problem that trades off expected return and risk, defined as the standard deviation of the portfolio returns. Since then, the method has been extended to include many practical constraints and objective terms, such as transaction cost or leverage limits. Despite several criticisms of Markowitz’s method, for example its sensitivity to poor forecasts of the return statistics, it has become the dominant quantitative method for portfolio construction in practice.
This talk describes an extension of Markowitz’s method that addresses many practical effects and gracefully handles the uncertainty inherent in return statistics forecasting. Like Markowitz’s original formulation, the extension is also a convex optimization problem, which can be solved with high reliability and speed.
Ron Kahn Global Head of Systematic Investment Research, BlackRock
 Ronald Kahn

Global Head of Systematic Investment Research, BlackRock
Ronald N. Kahn, PhD, Managing Director, is Global Head of Systematic Equity Research at BlackRock. He has overall responsibility for the research underpinning the Systematic Active Equity (SAE) products.
His service with the firm dates back to 1998, including his years with Barclays Global Investors (BGI), which merged with BlackRock in 2009. Prior to joining BGI, he worked as Director of Research at Barra, where his research covered equity and fixed income markets.
Ronald Kahn is a well-known expert on portfolio management and quantitative investing. He has published numerous articles on investment management, and, with Richard Grinold, authored the influential book Active Portfolio Management: Quantitative Theory and Applications. The two of them are the 2013 winners of James R. Vertin award, presented periodically by the CFA Institute to recognize individuals who have produced a body of research notable for its relevance and enduring value to investment professionals. He is a 2007 winner of the Bernstein Fabozzi/Jacobs Levy award for best article in the Journal of Portfolio Management. He serves on the editorial advisory boards of the Financial Analysts Journal, the Journal of Portfolio Management and the Journal of Investment Consulting. The 2007 book How I Became a Quant includes his essay describing his transition from physics to finance.
He earned an AB degree in physics, summa cum laude, from Princeton University, and a PhD in physics from Harvard University. He was a post-doctoral fellow in physics at University of California, Berkeley.
It will be Awesome
Final details are in the post.
Matthias Uhl Head of Analytics & Quantitative Modelling, UBS Asset Management
 Matthias is head of Analytics & Quantitative Modelling (AQM) in Investment Solutions at UBS Asset Management, the global lead for sentiment analytics at UBS Group, and a lecturer at the University of Zurich. Previously, he was Chief Investment Officer at FLYNT Bank AG, has worked as quantitative strategist in the CIO Office at UBS Wealth Management, as FX and rates trader at UBS Investment Bank, as commercial banker at Deutsche Bank, and as economist at KOF Swiss Economic Institute. Matthias holds a Ph.D. in applied macroeconomics and behavioral finance from ETH Zurich, a Master of Science from Oxford University and two Bachelor of Arts degrees from the American University of Paris.
Matthias has published his research in various academic journals, such as the Journal of Portfolio Management, Finance Research Letters, Journal of Derivatives, and Journal of Behavioral Finance, among others.
Allocating Portfolio Tail Risk: Kurtosis-Based Factor Risk Parity
Inspired by Ed Fishwick’s talk at last year’s LQG seminar, we introduce the Kurtosis-based Factor Risk Parity (KFRP) method for portfolio optimization. In contrast to conventional risk parity methods, KFRP evaluates risk contributions at the factor level and uses kurtosis as a risk measure. This allows to distribute tail risks in the factor investing framework. The paper establishes a comprehensive theoretical foundation and presents a flexible optimization framework that accommodates short selling.
The empirical application includes an out-of-sample analysis with fundamental and statistical factors, analyzed across diversified and equity-only portfolios. Results show that the KFRP method outperforms traditional Volatility-based Factor Risk Parity (VFRP) in managing risks, while maintaining strong financial efficiency. Moreover, we highlight the importance of tailoring risk management to portfolio characteristics and identify trade-offs between fundamental and PCA factors.
Dr Svetlana Borovkova. Associate professor of quantitative finance at Vrije Universiteit Amsterdam
 Dr Svetlana Borovkova is an associate professor of quantitative finance at Vrije Universiteit Amsterdam and the Head of Quant Modelling at risk consulting firm Probability & Partners. She has over 60 publications in scientific and professional journals and is a frequent speaker at major quant finance and risk events such as RiskMinds and QuantMinds. Her columns and blogs regularly appear in LSEG publications, Financial Investigator and other financial outlets.
“?” A look at the IS-LM model in the real world outside of the classroom.
“?” A look at the IS-LM model in the real world outside of the classroom.
Central banks use monetary policy to meet economic objectives – commonly in the form of an inflation target: when a lower inflation rate is desired, the central bank increases the interest rate in order to slow growth, and when a high inflation rate is desired, the central bank decreases the interest rate. The theoretical economic underpinning of this approach is provided by the well-known IS-LM model, as described by Ed Fishwick at the LQG conference a couple of years ago.
It is unusual for the labour force to work for the whole of their lives. Usually, a retirement age is reached whereafter the worker no longer receives income for their labour. After retirement, the individual will still need to consume and must therefore find a replacement for that income. That replacement income is usually generated from a pension fund into which the individual saved throughout their working life. In this case, a reduction in the interest rate can negatively impact saving for retirement and, all else equal, will cause a worker to need to save more to meet their income replacement needs. We show that this effect causes the investment-savings (IS) curve to exhibit a turning point: once the interest rate becomes low enough, saving increases and the economy slows.
Worse still, there is a limit to the amount an individual can save. Therefore, if the interest rate decreases far enough, such that an individual is saving to the maximum possible degree, then any further reduction in the interest rate must cause a saver to seek a higher rate of return of their savings: i.e. a reach for yield. This causes economic growth to be unchanged with such interest rate changes, hence the IS curve becomes vertical.
There is ample evidence of such reaching for yield during the ultra-low interest rate environment, and we therefore argue that whilst central banks are using a tool such as the IS_LM model to set monetary policy, they are being naïve in their resumed form of the IS curve. Had they instead adopted the curve we derive then it would have demonstrated the foolhardiness of policy from 2008 to 2023 and offered an explanation of the extreme reach for yield that was observed.
Remarkably, the saviour of developed world from this demonstrably destabilising monetary policy was Vladimir Putin. His invasion of Ukraine caused inflation to rise sharply and triggered the world’s central banks to escape the funk of zero-interest rate policy and aggressively raise interest rates.
We show that the interest rate rise was so fast that it caused a jump across this perverse segment of the IS-curve into a conventional environment. However, that sharp move has left the reach for yield, particularly into less liquid assts, yet to be unwound. We conclude by discussing what effects this might still have an financial assets, in particular we argue that this is causing problems in the housing market – especially rentals – and suspect it will cause difficulties in the new foray of investors into private markets.
David Buckle – Chairman of INQUIRE UK

David Buckle
Chairman INQUIRE UK
David has been in the asset management industry for over 25 years, primarily as a portfolio manager or analyst. He has been made redundant many more times than he would have liked and therefore has worked for many blue-chip asset managers including JP Morgan Asset Management, Putnam Investments, Merrill Lynch Investment Managers, Blackrock, UBS Global Asset Management and Fidelity. He also ran an investment boutique for several years deploying overlay strategies. Throughout his career he has contributed to the investment literature, especially in the area of the theory of active management.
Having become a bit disenchanted with the industry of late, David now has a plurality of roles, including being the CEO and CIO of a tiny real asset investment company, running a handful of multi asset portfolios, and is the chairman of the Institute for Quantitative Investment Research (INQUIRE). He spends much of his time authoring articles and is in the process of writing a couple of books on investment matters.
David’s background is as a Phd. mathematician and that discipline remains his hobby. His most recent article is the interpretation of some cuneiform mathematics scribed on a Babylonian stone from 2000BCE.
A Unified Model Of Investor Utility And Asset Pricing
Dan will present this work which develops a new and intuitive expression of investor utility. To motivate the discussion, it starts with an empirical test that is a conjecture of a general valuation model applied to three popular publicly traded market composites. This experiment evaluates the quality of price estimates produced by the suggested model and compares it to the quality of a traditional valuation model that reflects mean and variance efficiency. Thereafter, the work resorts to conceptual means to justify the usage of the proposed model in the experiment. The model derivation is grounded in maximization of the logarithm of investor wealth. The main difference between the utility function developed herein and previous models that build on a relationship with the logarithm of wealth is that the new model explicitly incorporates the investor time horizon, discretionary consumption, and the effect of potential investor default as determinants of loss aversion. The new utility form treats both external borrowing and non-discretionary future consumption as leverage, and it assumes that investor equity absorbs all losses before affecting the ability to repay debt or finance future non-discretionary consumption. In addition to developing a portfolio optimization objective, the utility function gives the ability to explicitly estimate the fair value of a portfolio – a result which supports the conjecture model used in the initial empirical test. The new utility and valuation model is free of most constraints and assumptions in existing investor utility models with respect to the statistical properties of the portfolio stochastic process. The model also aligns closely with the principles of risk aversion in the Expected Utility Theory.
Dan DiBartolomeo President and Founder Northfield Information Services, Inc.

Mr. diBartolomeo is President and founder of Northfield Information Services, Inc. Based in Boston since 1986, Northfield develops quantitative models of financial markets. He sits on boards of numerous industry organizations include IAQF and CQA, and is a director and past president of the Boston Economic Club. His publication record includes fifty books, book chapters and research journal articles. In addition, Dan has been a Visiting Professor at Brunel University, and has been admitted as an expert witness in litigation matters regarding investment management practices and derivatives in both US federal and state courts. He became editor in chief of the Journal of Asset Management at the start of 2019.
Strategic Arbitrage in Segmented Markets
We propose a model in which arbitrageurs act strategically in markets with entry costs. In a repeated game, arbitrageurs choose to specialize in some markets, which leads to the highest combined profits. We present evidence consistent with our theory from the options market, in which suboptimally unexercised options create arbitrage opportunities for intermediaries. Using transaction-level data, we identify the corresponding arbitrage trades. Consistent with the model, only 57% of these opportunities attract entry by arbitrageurs. Of those that do, 49% attract only one arbitrageur. Finally, our paper details how market participants circumvent a regulation devised to curtail this arbitrage strategy.
Svetlana Bryzgalova - Assistant Professor of Finance at London Business School

Svetlana Bryzgalova
Assistant Professor of Finance at London Business School
Svetlana Bryzgalova is an Assistant Professor of Finance at London Business School. Her research is focused on empirical asset pricing and macrofinance. In particular, she uses financial econometrics and data science to better understand the cross-section of asset returns, and the sources of systematic risk in the economy. Her research received numerous awards, including Best Paper in Asset Pricing awards from the SFS Cavalcade and Midwest Finance Association. She holds a PhD from London School of Economics, and previously worked at Stanford GSB before joining LBS.
The next AI crisis
The rapid adoption of artificial intelligence (AI) is transforming the financial industry. AI will either increase systemic financial risk or act to stabilise the system, depending on endogenous responses, strategic complementarities, the severity of events it faces and the objectives it is given. AI’s ability to master complexity and respond rapidly to shocks means future crises will likely be more intense than those we have seen so far.
Jon Danielsson, Professor of Finance at the London School of Economics
Jon Danielsson

Professor of Finance, London School of Economics.
Jon Danielsson is a renowned financial economist and a professor of finance at the London School of Economics. He is the director of the Systemic Risk Centre, a research center that aims to understand the causes and consequences of systemic risk in the financial system. Danielsson has made significant contributions to the field of financial risk management and has extensive expertise in financial regulation, financial policy, the drivers of long term risk, and investment. Danielsson received his PhD in the economics of financial markets, and since then, his research has focused on how economic policy can lead to prosperity or disaster. He is an authority on both the technical aspects of risk forecasting and the optimal policies that governments and regulators should pursue in this area. He has written three highly regarded books on these topics: “The Illusion of Control” (Yale University Press, 2022), “Financial Risk Forecasting” (Wiley, 2011), and “Global Financial Systems: Stability and Risk” (Pearson, 2013). His books have been widely recognized as important contributions to the field and have been included in the Financial Times best economics books of the year (2022). In addition to his books, Danielsson has also contributed numerous academic papers on systemic risk, artificial intelligence, financial risk forecasting, financial regulation, and related topics to leading academic journals, including the Review of Financial Studies and the Journal of Econometrics. His research has been widely cited and has had a significant impact on the field. At the LSE, Danielsson teaches courses in technical risk forecasting and on how the global financial system operates. He is highly respected by students and is considered one of the most knowledgeable experts on the subject. He has also worked for the Bank of Japan and the International Monetary Fund, providing valuable insights and expertise on financial risk management and regulation. Danielsson’s practical and authoritative perspective on financial risk and the financial system means he is regularly interviewed by media organizations including the BBC, Financial Times, The New York Times, and The Wall Street Journal. He is also a regular speaker at conferences and events related to financial risk management, long term risk, investment and regulation.
Passive Aggressive? The Impact of Climate Indices on Capital Costs
Passive Aggressive? The Impact of Climate Indices on Capital Costs
Joint work with Katja Scherer, TU Dortmund
Green finance will lower carbon emissions if it materially increases the capital costs of polluting firms. For this to happen, substantial green capital is required. Climate Change and ESG indices play an essential role in this. They serve as ESG or climate investors benchmarks and can guide the required investment flows. But how successful are these investments in impacting the capital costs of companies? Our paper shows that popular climate indices display statistically significant but economically insufficient changes in capital costs relative to their respective parent indices. Without an impact on capital costs, these investments will not lead to the hoped-for changes in corporate investment projects.
Bernd Scherer Head of Portfolio Implementation at Abu Dhabi Investment Authority (ADIA)

Bernd is an experienced CIO and academic writer. He currently works as the Head of Portfolio Implementation at Abu Dhabi Investment Authority (ADIA), one of the world’s largest sovereign wealth funds.
He has more than 20 years of experience in senior management positions for various hedge funds, asset management companies, and banks in New York, London, Vienna, and Frankfurt, where he designed and implemented quantitative investment strategies, products and processes, and successfully reorganized investment teams. Bernd is also a former Professor of Finance at EDHEC Business School, where he taught and researched on asset pricing, machine learning, portfolio construction, and risk management. He published more than 80 peer-reviewed articles in leading academic and practitioner Journals and currently serves on the editorial board of the Financial Analysts Journal.
It is risky to forecast
It is especially risky to forecast the future.
Ed Fishwick Senior Managing Director, Chief Risk Officer, BlackRock and Chairman of the London Quant Group

Ed Fishwick
Senior Managing Director, Chief Risk Officer, BlackRock
Ed Fishwick is the Chief Risk Officer, Global Head of Risk and Quantitative Analysis, and a member of the Global Executive Committee at BlackRock. He is responsible for the investment and enterprise risk of BlackRock. Prior to taking on his current responsibilities in 2022, Mr. Fishwick served as the Global Co-Head of the Risk and Quantitative Analysis Group in London for 15 years. His service with the firm dates back to 2003.
Mr. Fishwick’s previous positions in the industry include Head of Risk Management, and Investment Process Research at AXA Investment Managers, and Head of Research at Franklin Portfolio Managers in Boston.
Ed is the Chairman of the London Quant Group.
Accommodation
Robinson College
Venue: Robinson College, Grange Road, Cambridge CB3 9AN
Seminars will be delivered in the Crausaz Wordsworth Building – “The CWB” on the Robinson College site map.
Download the Summary Agenda / Download the Detailed Agenda
Robinson College has delightful grounds and facilities close to the centre of Cambridge. The seminar room is marvellous:
The college bedrooms rooms can be seen here :
One ticket – for the seminar, all meals and accommodation – what a deal!
All room bookings are for 3 nights including the Friday night.
College rooms are obviously college rooms – they are not 5* hotel quality but perfectly functional and comfortable.
Guests: Should you wish to bring a guest, please buy an additional guest ticket to cover the social events and meals only. No seminar attendance is included with the guest ticket.
There is car parking available. If you need parking it is important that you buy an additional parking only ticket.
There are some twin rooms available. Please only book a twin if you really need one.
If you do not want to stay in college please make your own arrangements. The LQG does not reserve hotel rooms.
Dinners and lunches
Robinson college is proud of its catering and the LQG shall make optimal use of it.
To ensure some variety we will have dinner on Thursday at a local-ish restaurant in Madingley. Weather prmitting the energetic will walk to Madingley.
- Wednesday night – Informal BBQ / buffet dinner on arrival
- Thursday lunch – hot and cold buffet
- Thursday dinner – 3 course dinner in Madingley
- Friday lunch – hot and cold buffet
- Friday dinner – 3 course dinner
- Saturday lunch – haven’t you got a home to go to??
Breakfast is included for all staying in college rooms.
Punting – Cambridge
The link between a quant conference and punting is of course the “quant”. Quant is the proper name for the pole used for punting. The punting opportunity is why you are asked for your T-shirt size when you register. You can of course wear your T-shirt during the seminar as well as for punting when It may be supplemented (or disguised) as required, according to temperature and propriety. The T-shirt has a helpful reminder of the dictionary definition of a quant.
For over 3o years the LQG annual seminar included the annual punting challenge. The 2 day format for this seminar does not allow for the punting challenge to be part of the seminar. However… those who choose to stay for dinner in college on Friday will clearly want to work off some energy on Saturday …
… which will be an excellent opportunity to demonstrate elegance, skill, fitness, and power in punting as well as making and keeping friends.
Punting is both easier… and can be harder than it looks – but above all it is to be enjoyed with friends in a beautiful setting. So Saturday will provide a great opportunity to enjoy punting along the backs of the colleges in Cambridge. The more adventurous may choose to make a trip out to Granchester.
Clothes for punting
Please bring loose fitting informal clothes to wear for the punting.
There is the possibility of getting wet as rain is always a possibility.
Trainers or sailors’ deck shoes are ideal.
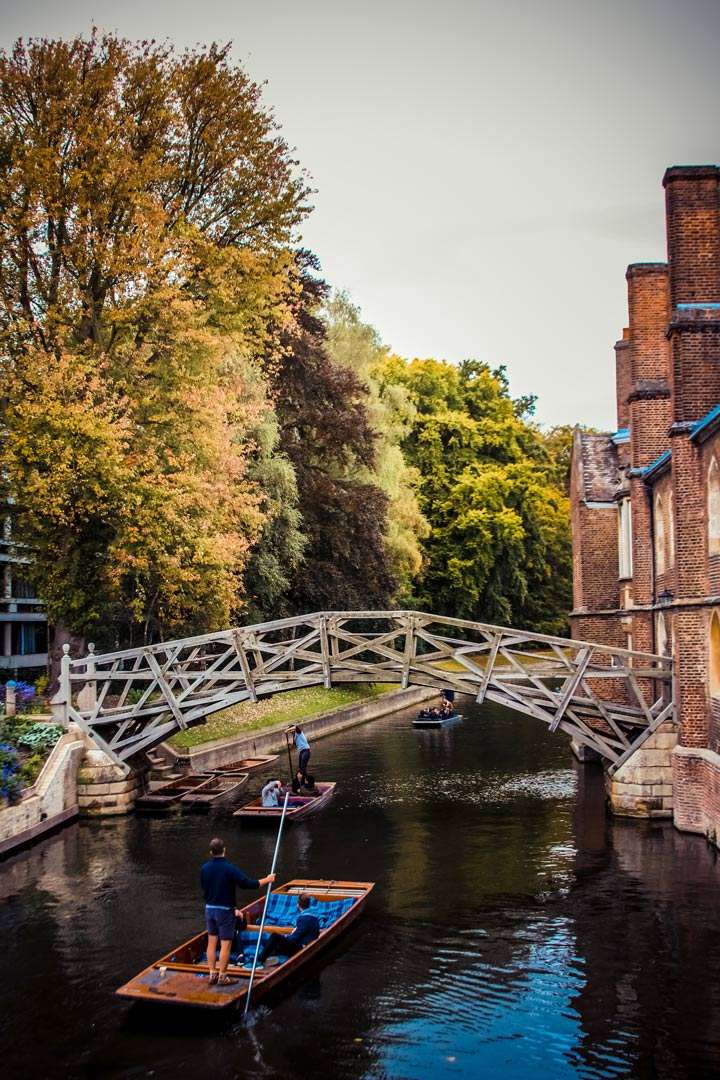
punting
No there is no competition!
Punting with style

Cambridge-20150913
Very cool – punting with style
