LQG Seminars
ENCORE – Engaging New Controversial Original Rigorous Entertaining
Trust Me, I Am A Robo-Advisor
Seminar by Bernd Scherer
14th March 2023 – In-Person and On-Line – Hybrid
The LQG is very grateful to BlackRock for hosting this seminar.
In this seminar Dr. Scherer offers cross-sectional insights into Robo-advisory portfolio structures. For this purpose, the authors scrape portfolio recommendations for 16 German Robo-advisors. Collectively their sample accounts for about 78% of assets in the German Robo-advisory market. They analyze about 243.000 pairs of recommended portfolios and their corresponding client characteristics. Their results show that current Robo-advice offers limited individualization. Variables that matter in modern portfolio-choice like the amount and nature (beta) of human capital or shadow assets are largely ignored. Instead, portfolio recommendations are designed to meet investor preconceptions or the regulator’s understanding of portfolio choice. While ensuring consumer trust and regulatory approval makes business sense, it also limits the economic benefits of Robo-advisors.
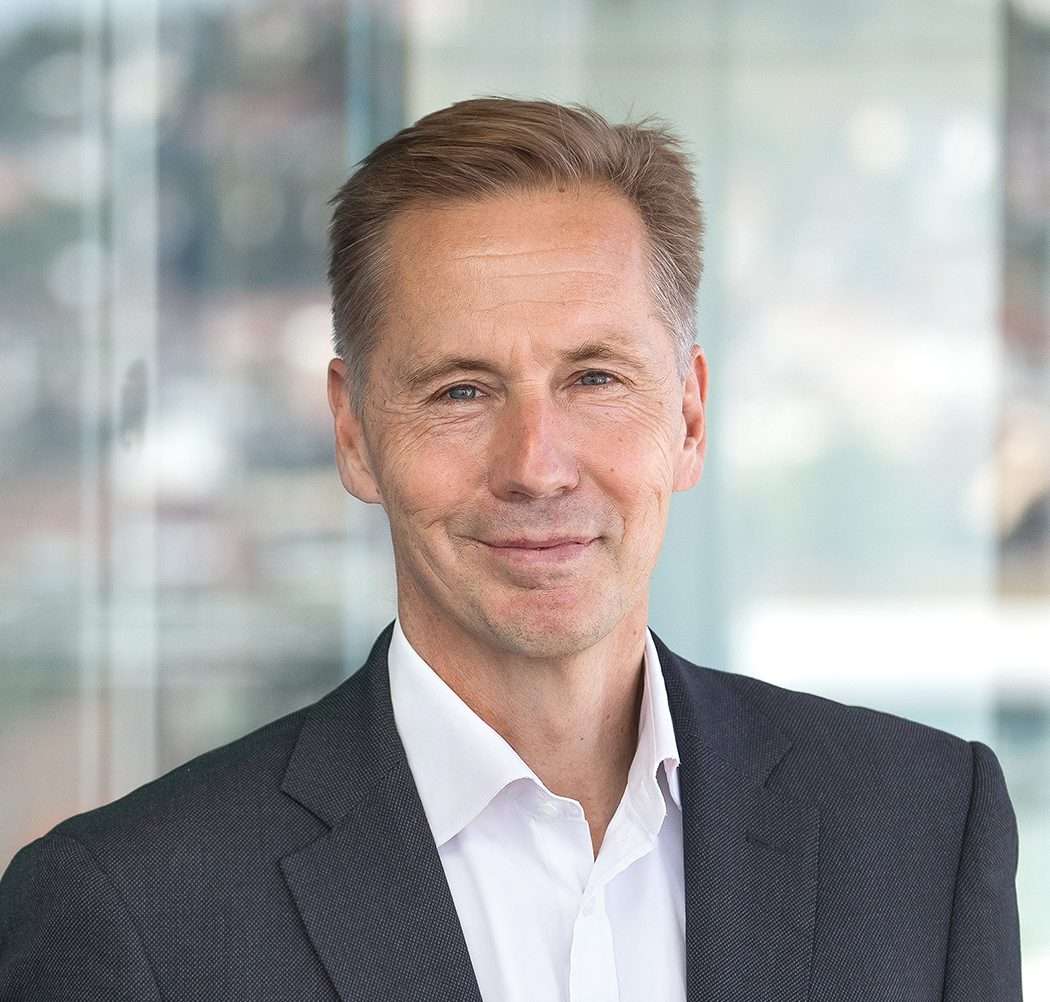
Bernd Scherer
Chief Investment Officer | Geschäftsführer
LBBW Asset Management
Bernd is a long term friend and frequent speaker at the LQG – this will be his 15th seminar! He prefers uncompromising language and misses London (Richmond) more than ever. He will be in London in person and is very much looking forward to seeing the LQG community.
Professionally, Bernd is an ex Professor of Finance (EDHEC) and experienced CIO. He combines extensive investment experience across all asset classes with strong academic credentials in asset pricing, quantitative investment strategies, statistics, econometrics, machine learning, portfolio construction and risk model construction. During his professional career, he worked in senior management positions for various hedge funds, asset management companies and banks in New York, London, Vienna and Frankfurt. He designed quantitative investment strategies, investment processes, portfolio engineering platforms, robo-advisors, investment products and successfully re-organised investment teams.
Bernd’s academic work has been published in Journal of Banking and Finance, Journal of Financial Markets, Journal of Empirical Finance, Finance Research Letter, Journal of Economics and Statistics,
Quantitative Finance, Journal of Derivatives, Journal of Portfolio Management, Financial Analysts Journal, Journal of Alternative Investment Strategies, Journal of Financial Data Science, Journal of Investment Management,
Financial Markets and Portfolio Management, Journal of Asset Management , Journal of Applied Corporate Finance, Journal of Trading, Journal of Risk Model Validation, Journal of Hedge Funds and Derivatives, Risk, Journal of Wealth Management. Bernd is also author/editor of 8 books on quantitative asset Management for Risk, Springer and Oxford University Press.
