The LQG will debate the motion: This house believes that
Risk Is A Fate Not A Choice.
Proposer: Jon Danielsson
and
Opposer: Ed Fishwick
LQG events in 2022.
The LQG will debate the motion: This house believes that
Risk Is A Fate Not A Choice.
Proposer: Jon Danielsson
and
Opposer: Ed Fishwick
Dan diBartolomeo will discuss spectacular failures in past risk management practice and warns of commonly used shortcuts that may lead to the next disaster.
Blockchain, the Essence of Bitcoin and a Mathematical Introduction to Bitcoin – the machines, maths and people that make it work.
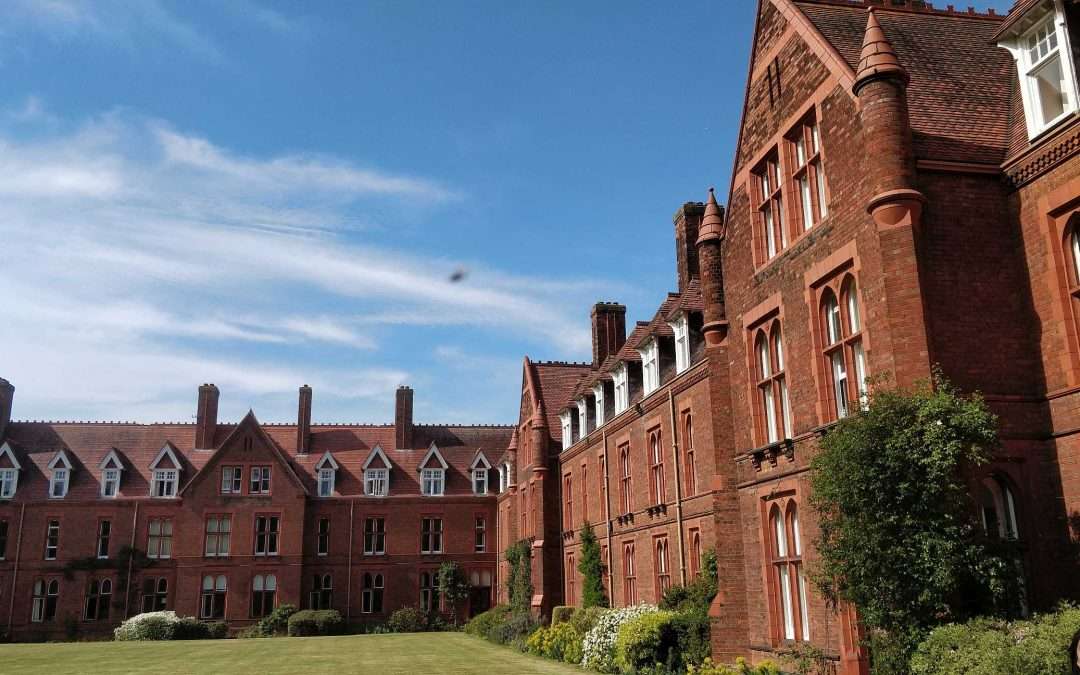
LQG 31/08/22 to 02/09/22 In-Person Autumn Seminar at Girton College, Cambridge with 11 speakers of international renown – after two years of lockdown it is great to be back!
LQG July 2022 seminar delivered in person by Andrew Ang of BlackRock – Asset Allocation with Crypto: Application of Preferences for Positive Skewness – Beware there be dragons!
Explore the types and sources of inflation and then explore the various impacts on assets’ prices. That knowledge can help guide both strategic and tactical asset allocations for both return and risk improvements.
The significant benefits of using Multi Asset Class Factor Premia for overlay strategies over an investor’s lifecycle
The calming of short-term market fears and its long-term consequences: The central banks’dilemma – J.P. Zigrand
This paper models weights and parameters as uncertain. Evaluating a portfolio across the range of possibility measures risks better and surfaces latent fragility. Contributions to risk are reported with a center and spread.
LQG 08/02/22 – On-Line – “Enhanced income and costless protection” : Good options, poor choices and the hidden costs of a supposedly free lunch – David Buckle. This seminar aims to stimulate thought and discussion as the analysis’ conclusions are likely to be counter intuitive to some and controversial to others.